Gold's breakthrough above US$5,000 and silver's surge through US$100 signal this year could be one for the history books for metal traders (one way or another).
Quick facts
- Elevated safe-haven demand lifts Gold targets from US$5,400 to US$6,000 after early-year US$5,000 breakout.
- Artificial intelligence (AI) and data-centre infrastructure ramp-up could help drive silver and copper demand.
- Continued geopolitical uncertainty and shifting monetary policy could trigger metal volatility throughout the year.
Top 5 metals to watch in 2026
1. Gold
Gold's breakout over US$5,100 arrived three quarters ahead of some forecasts. With Bank of America quickly raising its end-of-year target to US$6,000 and Goldman Sachs projecting US$5,400, the safe-haven commodity remains the biggest asset in focus for 2026.
Key drivers:
- Central banks are currently buying an average of 60 tonnes of gold per month, compared to 17 tonnes pre-2022.
- Two Fed rate cuts are priced in for 2026, reducing the opportunity cost of holding non-yielding assets like gold.
- Trump tariff policies, Middle East tensions, and fiscal sustainability concerns are keeping safe-haven demand elevated.
- Gold's share of total financial assets hit 2.8% in Q3 2025, with room to grow as retail FOMO kicks in.
What to watch
- Jerome Powell is set to be replaced as Fed chair in May 2026. Actual policy direction post-replacement may differ from current market expectations for cuts.
- If geopolitical hedges into safe havens remain or if there is an unwinding like post- 2024 US election.
- The potential weaponisation of dollar asset holdings by European nations as a response to US tariffs.
2. Silver
Silver is the metal that has benefited the most from the 2025 AI boom, with its surge to US$112 all-time-highs to kick off 2026 (70% above fundamental value as per Bank of America signal), demonstrating its volatile potential.
Key drivers
- Industrial demand from AI infrastructure, solar, and electric vehicles (EVs), semiconductors and data centres currently has no viable substitute for silver's conductivity.
- Six consecutive years of supply deficit, with above-ground stocks depleting and recycling bottlenecks limiting secondary supply.
- Policy optics may matter. The US decision to add silver to its list of “critical minerals” has been cited as a potential factor in volatility, including around trade policy risk.
- Retail participation can amplify price moves, particularly when the demand for gold becomes “too expensive”.
What to watch
- If solar panel demand continues its trajectory, or if 2025 was the peak.
- Whether the recycling supply responds to record prices by increasing silver refining and material processing capacity.
- How exchange inventory and lease rates move as potential signals of physical tightness.
3. Copper
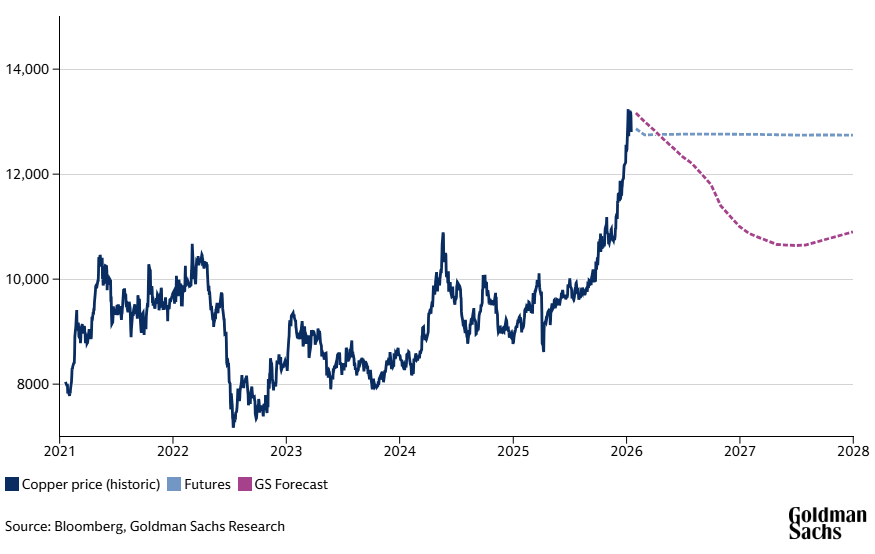
Copper's 2026 story hinges on continued data centre demand, renewable energy infrastructure growth, and China's struggling property market.
Key drivers
- Data centre copper consumption is projected to hit 475,000 tonnes in 2026, up 110,000 tonnes from 2025.
- Worker strikes in Chile and Grasberg restart delays are keeping the Copper market structurally tight.
- The US tariff decision on refined copper imports is expected in mid-2026 (15%+ currently anticipated), creating potential stockpiling and trade flow distortions.
- Goldman Sachs has forecast that power grid infrastructure and EV buildout could add "another United States" worth of copper demand by 2030.
- Current Chinese property weakness is creating demand uncertainty, potentially offsetting infrastructure spending.
What to watch
- Whether Grasberg ramps production smoothly or faces further setbacks.
- Chinese property market stimulus effectiveness.
- Actual tariff implementation timing and magnitude.
- Yangshan premium movements signalling real physical demand versus financial positioning.
4. Aluminium
Trading near three-year highs of US$3,200, aluminium faces continued tightness into 2026 as China's capacity ceiling forces global markets to adjust.
Key drivers
- China's 45 million tonne capacity cap was reached in 2025. For the first time in decades, Chinese output cannot expand, potentially ending 80% of global supply growth.
- As copper prices increase, Reuters has reported that some manufacturers have been substituting aluminium for copper in certain applications as relative prices shift.
What to watch
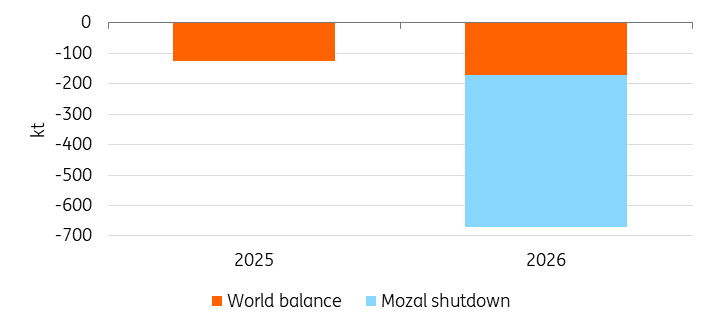
- South32 has said Mozal Aluminium is expected to be placed on care and maintenance around 15 March 2026, thus removing Mozambique's 560,000 tonne significant supply.
- If Indonesian and Chinese offshore capacity additions can compensate for Chinese domestic ceiling.
- Century Aluminium's 50,000 tonne Mount Holly restart in Q2 could provide a signal for the broader industry as the smelter is expected to reach full production by 30 June 2026.
5. Platinum
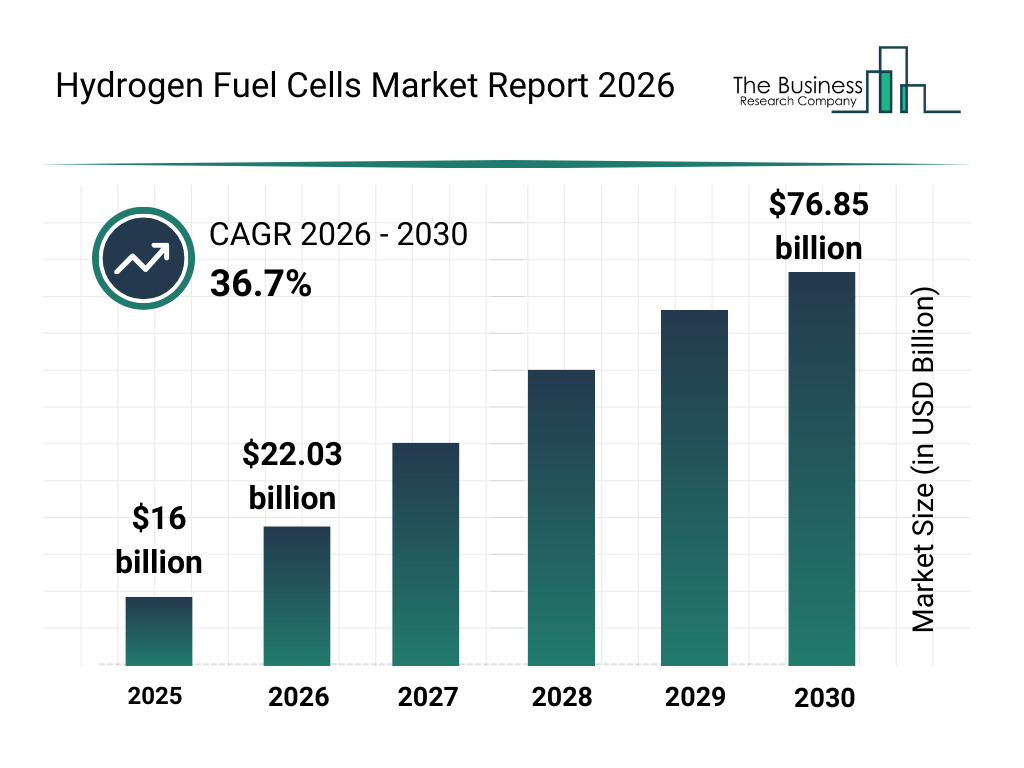
Platinum's breakout above US$2,800 follows three consecutive years of supply deficit and increased adoption of hydrogen fuel cells (for which it is a vital component).
Key drivers
- The World Platinum Investment Council (WPIC) has forecast a significant supply deficit of 850,000 ounces in 2026 which could drain inventories, with limited new production coming online.
- WPIC forecasts 875,000 to 900,000 oz uptake by 2030 for heavy-duty trucks, buses, and green hydrogen electrolysers.
- Palladium-to-platinum substitution in catalytic converters is increasing in EV production.
What to watch
- Supply response from producers. Platreef and Bakubung are adding 150,000 oz, but production discipline could limit a broader ramp-up.
- US tariffs on Russian palladium could create spillover demand for platinum in EV production.
- The pace of hydrogen infrastructure investment and heavy-duty vehicle adoption rates in Europe, China, and US.
- Chinese jewellery demand could come into play. Just a 1% substitution from gold could widen the platinum deficit by 10% of the global supply.
You can trade Gold, Silver, and other Commodity CFDs, including energies and agricultural products, on GO Markets.

Disclaimer: Articles are from GO Markets analysts and contributors and are based on their independent analysis or personal experiences. Views, opinions or trading styles expressed are their own, and should not be taken as either representative of or shared by GO Markets. Advice, if any, is of a ‘general’ nature and not based on your personal objectives, financial situation or needs. Consider how appropriate the advice, if any, is to your objectives, financial situation and needs, before acting on the advice. If the advice relates to acquiring a particular financial product, you should obtain our Disclosure Statement (DS) and other legal documents available on our website for that product before making any decisions.