The information provided is of general nature only and does not take into account your personal objectives, financial situations or needs. Before acting on any information provided, you should consider whether the information is suitable for you and your personal circumstances and if necessary, seek appropriate professional advice. All opinions, conclusions, forecasts or recommendations are reasonably held at the time of compilation but are subject to change without notice. Past performance is not an indication of future performance. Go Markets Pty Ltd, ABN 85 081 864 039, AFSL 254963 is a CFD issuer, and trading carries significant risks and is not suitable for everyone. You do not own or have any interest in the rights to the underlying assets. You should consider the appropriateness by reviewing our TMD, FSG, PDS and other CFD legal documents to ensure you understand the risks before you invest in CFDs. These documents are available here.
Any references to Australian or international shares, sectors, indices, ETFs, crypto-related stocks or other instruments are provided for market commentary and watchlist purposes only and do not constitute a recommendation, offer or solicitation to buy, sell or hold any financial product or adopt any investment strategy. International markets may involve additional risks, including currency fluctuations, regulatory differences, market structure differences, reduced liquidity and higher volatility. Company-specific, sector-specific and macroeconomic risks may also affect performance.
Commentary on geopolitical developments, economic data, central bank decisions, earnings, policy changes and other global or financial market events is based on information available at the time of publication and may change without notice. Such events can lead to sudden market moves, price gaps, reduced liquidity, wider spreads and increased volatility, particularly in leveraged products such as CFDs. Forward-looking statements, expectations and scenario analysis are inherently uncertain and should not be relied on as guarantees of future market behaviour or outcomes.
US CPI data expected to rise in September as markets reassess Fed rate outlook

- The US Consumer Price Index is expected to rise by 3.6% YoY in September.
- Annual core CPI inflation is expected to edge higher to 2.5% from 2.4% in August.
- The inflation report could influence the Fed’s policy outlook and drive the US Dollar valuation in the near term.
The US Bureau of Labor Statistics (BLS) will publish the September Consumer Price Index (CPI) data on Wednesday. The report is expected to show a further increase in headline prices and a small uptick in annual core inflation. Any divergence from analysts’ estimates could influence the Federal Reserve’s (Fed) policy outlook and impact the US Dollar’s (USD) valuation.
The monthly CPI is forecast to rise 0.6%, following the 0.4% increase recorded in August, while the annual reading is seen edging higher to 3.6% from 3.4%. Core CPI figures, which exclude volatile food and energy prices, are expected to rise 0.2% and 2.5%, on a monthly and yearly basis, respectively.
Crude Oil prices rose sharply in the first half of September before correcting lower in the second half. Still, West Texas Intermediate (WTI) gained about 5% for the month. In this period, diesel prices per gallon in the US increased from $5.6 to $6.38, rising about 14%.
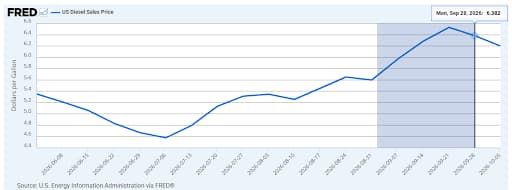
Chart: https://fred.stlouisfed.org/series/GASDESW
Analysts at Societe Generale highlight diesel’s outsized role in shaping US inflation dynamics, noting that “few fuels are as deeply embedded in the US economy as diesel, with its importance spanning freight, agriculture, construction and industry.” This deep integration creates “a clear transmission channel from diesel prices into broader inflation,” and the bank stresses that “the empirical relationship is striking – diesel price changes explain roughly 70% of the variation in US inflation surprises.” Societe Generale calculates that “a 1% YoY increase in diesel prices is associated with a 0.06 percentage point rise in the inflation surprise,” underscoring how moves in this single fuel can materially influence headline inflation outcomes.
How could the US Consumer Price Index report affect EUR/USD?
Some relatively cautious comments on further policy tightening from Fed policymakers and the disappointing September labor market caused investors to scale back bets for a 25 basis points (bps) interest rate hike in October. According to the CME FedWatch Tool, markets are currently pricing in about an 80% probability of a policy hold at the upcoming meeting.
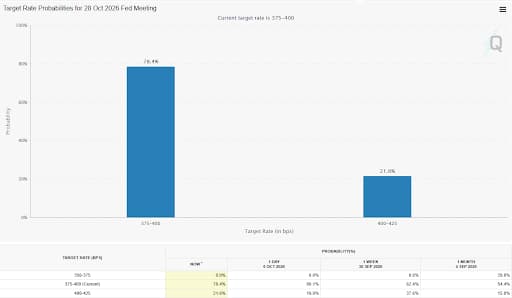
Fed Vice Chair for Supervision Michelle Bowman said there is "no urgent need for more rate moves this year," while Minneapolis Fed President Neel Kashkari told Bloomberg that if they keep raising rates, they will put different pressure on different parts of the economy. On a similarly cautious note, Fed Governor Christopher Waller said that they need to hike the policy rate further but added that they also need to be flexible about the pace. In the meantime, the Bureau of Labor Statistics reported that Nonfarm Payrolls rose by 29K in September, missing the market expectation of 90K by a wide margin, and the Unemployment Rate edged higher to 4.2% from 4.1% in August.
At this point, a significant upside surprise, at least a reading of 0.7% or higher, in the monthly CPI print could revive October rate hike expectations or confirm the federal funds rate will be higher than the current level in December, which currently has a probability of about 85%, as it would point to a spillover from high energy prices into the wider economy and consumer inflation. In this scenario, the USD could gather strength with the immediate reaction and cause EUR/USD to come under renewed selling pressure.
Conversely, a soft monthly inflation print of 0.4% or lower could reaffirm a policy hold in October. Even though such a reading is likely to weigh on the USD and help EUR/USD stabilize in the near term, it might not be enough to trigger a steady recovery, given markets’ waning confidence in the European Central Bank’s (ECB) ability to tighten monetary policy amidst the growing uncertainty surrounding France’s fiscal outlook and the widening spread between German and French government bonds, also called Obligations Assimilables du Trésor (OAT).
Finally, a monthly CPI print matching the market consensus, or coming in just 0.1 percentage points below it, could fail to materially alter the market pricing of the Fed rate outlook and have limited impact on the USD’s performance.
Analysts at MUFG/BTMU argue that Marine Le Pen’s, the main opposition party leader in France, fiscal plans are unlikely to materially alter the outlook for French government bonds before voters go to the polls, stating that “this alternative budget is unlikely to make much difference to the risks associated with OATs ahead of the election next year – especially given a plausible scenario of a presidential election run-off in the second round between Le Pen and the hard-left candidate Jean-Luc Melechon, who is now usually polling second on around 20% versus Le Pen on around 30%.” Against this backdrop of persistent political uncertainty and sensitivity to global rates moves, MUFG/BTMU conclude that “EUR/USD downside risks are set to prevail.”
Valeria Bednarik, Chief Analyst at FXStreet, notes: “The EUR/USD pair remains depressed near its lowest level since May 2025 in the 1.1150 price zone, and aims to extend its decline from a technical point of view. The daily chart shows the pair trading below all bearish moving averages, with the 20-day Simple Moving Average (SMA) gathering strong downward momentum at 1.1325. Technical indicators are turning marginally higher after reaching oversold readings, reflecting the near-term bounce rather than suggesting the pair has found an interim bottom.”
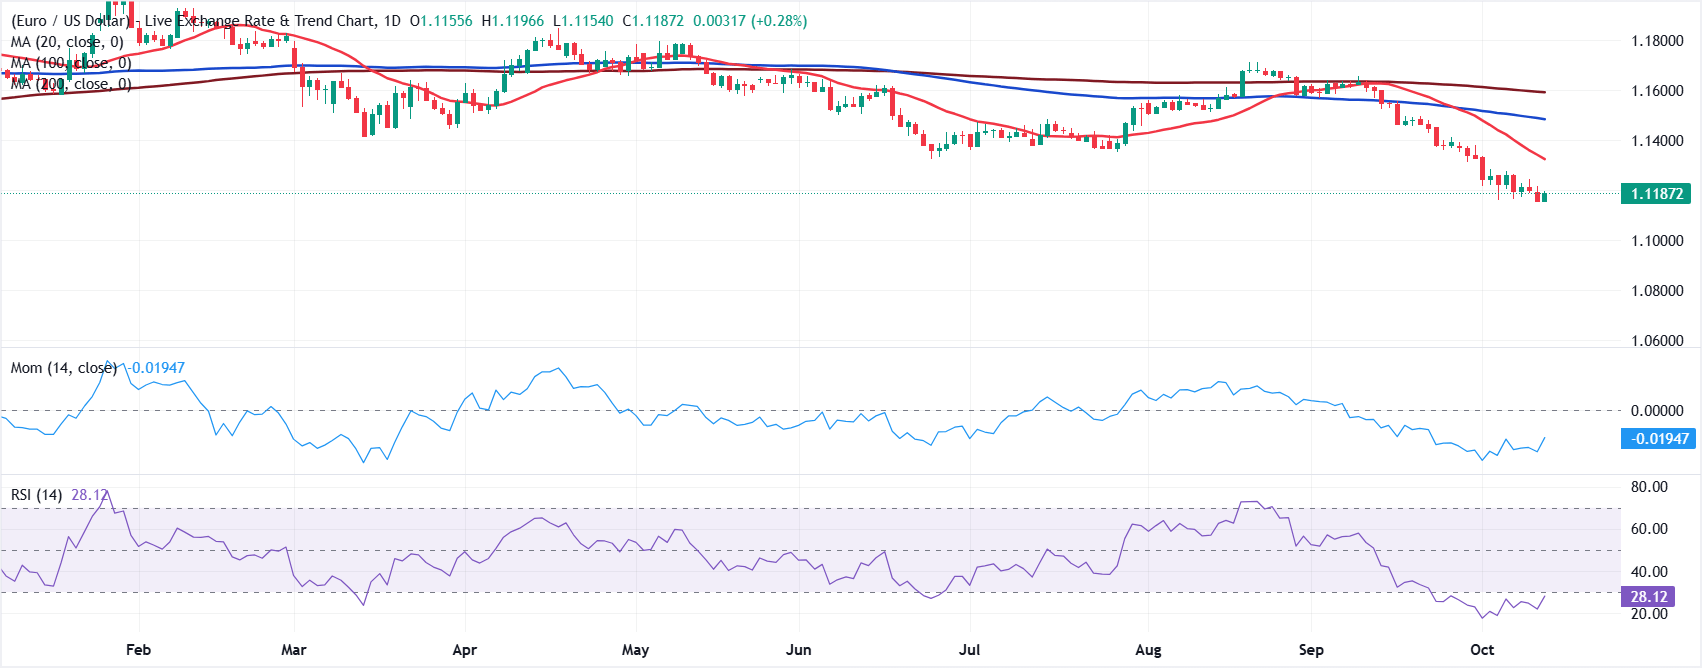
Bednarik adds: “Once the October low near 1.1150 gives up, EUR/USD can extend its slide initially towards the 1.1100 area, and then towards 1.1060. The next relevant support is the 1.1000 psychological threshold, although it seems unlikely that the pair will reach such a level just with the CPI release. Conversely, an extension of the ongoing recovery would meet initial resistance at around 1.1260, while once the area is cleared, the rally can continue towards the 1.1320 price zone.”
Inflation FAQs
Inflation measures the rise in the price of a representative basket of goods and services. Headline inflation is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core inflation excludes more volatile elements such as food and fuel which can fluctuate because of geopolitical and seasonal factors. Core inflation is the figure economists focus on and is the level targeted by central banks, which are mandated to keep inflation at a manageable level, usually around 2%.
The Consumer Price Index (CPI) measures the change in prices of a basket of goods and services over a period of time. It is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core CPI is the figure targeted by central banks as it excludes volatile food and fuel inputs. When Core CPI rises above 2% it usually results in higher interest rates and vice versa when it falls below 2%. Since higher interest rates are positive for a currency, higher inflation usually results in a stronger currency. The opposite is true when inflation falls.
Although it may seem counter-intuitive, high inflation in a country pushes up the value of its currency and vice versa for lower inflation. This is because the central bank will normally raise interest rates to combat the higher inflation, which attract more global capital inflows from investors looking for a lucrative place to park their money.
Formerly, Gold was the asset investors turned to in times of high inflation because it preserved its value, and whilst investors will often still buy Gold for its safe-haven properties in times of extreme market turmoil, this is not the case most of the time. This is because when inflation is high, central banks will put up interest rates to combat it. Higher interest rates are negative for Gold because they increase the opportunity-cost of holding Gold vis-a-vis an interest-bearing asset or placing the money in a cash deposit account. On the flipside, lower inflation tends to be positive for Gold as it brings interest rates down, making the bright metal a more viable investment alternative.
Economic Indicator
Consumer Price Index (MoM)
Inflationary or deflationary tendencies are measured by periodically summing the prices of a basket of representative goods and services and presenting the data as The Consumer Price Index (CPI). CPI data is compiled on a monthly basis and released by the US Department of Labor Statistics. The MoM figure compares the prices of goods in the reference month to the previous month.The CPI is a key indicator to measure inflation and changes in purchasing trends. Generally, a high reading is seen as bullish for the US Dollar (USD), while a low reading is seen as bearish.
Read more.Next release: Wed Oct 14, 2026 12:30
Frequency: Monthly
Consensus: 0.6%
Previous: 0.4%
Source: US Bureau of Labor Statistics
The US Federal Reserve (Fed) has a dual mandate of maintaining price stability and maximum employment. According to such mandate, inflation should be at around 2% YoY and has become the weakest pillar of the central bank’s directive ever since the world suffered a pandemic, which extends to these days. Price pressures keep rising amid supply-chain issues and bottlenecks, with the Consumer Price Index (CPI) hanging at multi-decade highs. The Fed has already taken measures to tame inflation and is expected to maintain an aggressive stance in the foreseeable future.
Related Articles